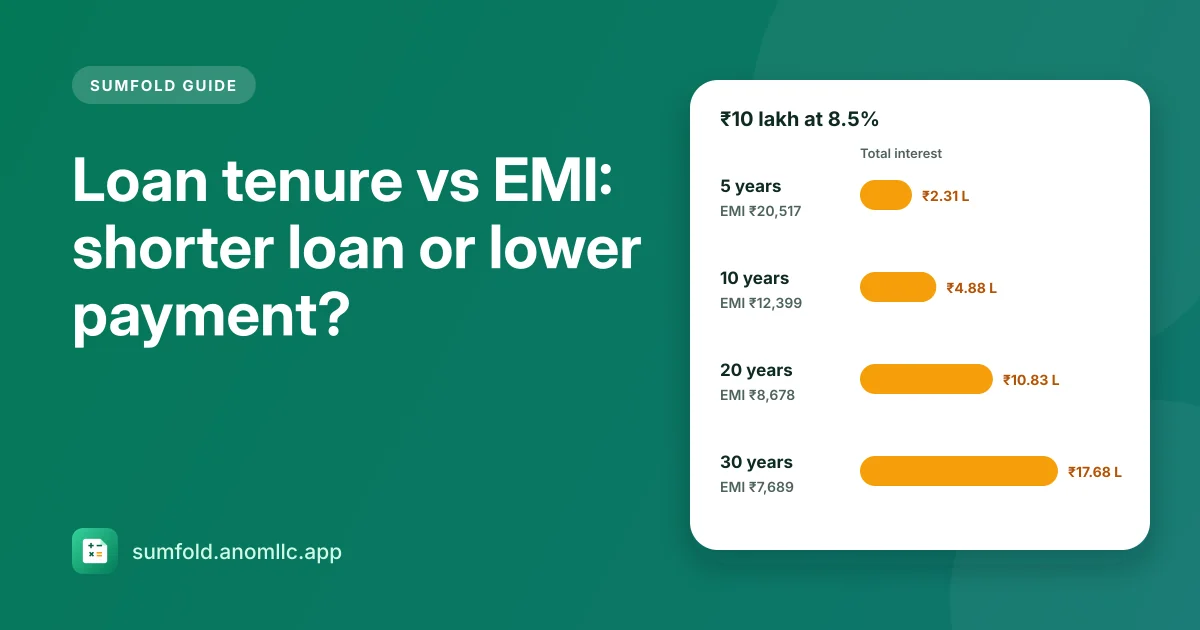
A longer loan tenure gives you a lower EMI, but you pay interest for more years, so the total cost goes up a lot. For a ₹10 lakh loan at 8.5%, stretching the term from 10 to 20 years cuts the EMI by about ₹3,700 a month but adds almost ₹6 lakh of interest. The best term is usually the shortest one whose EMI you can pay comfortably every month.
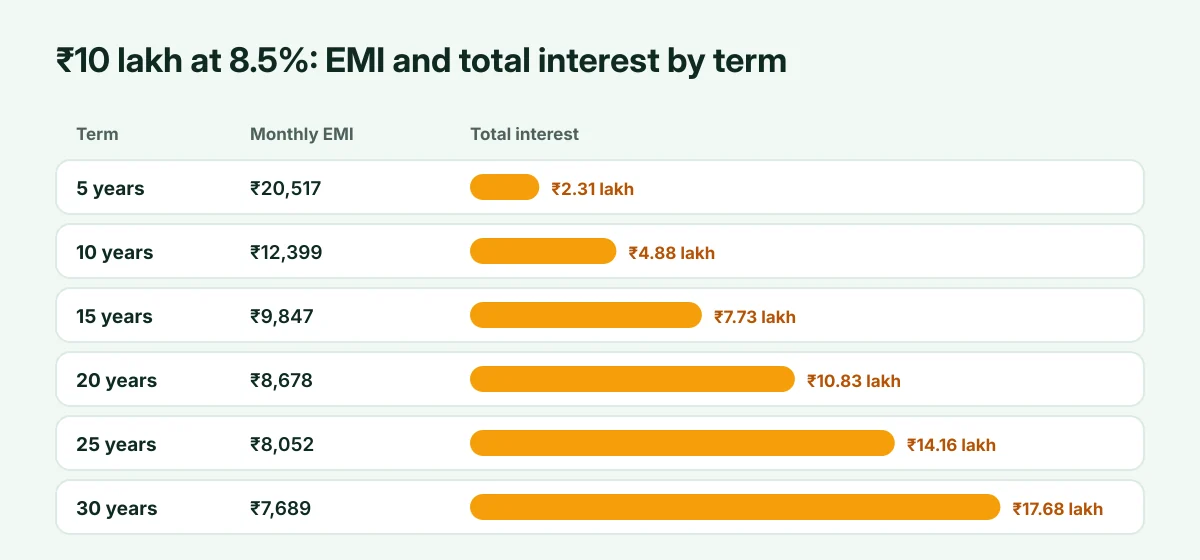
The numbers: ₹10 lakh at 8.5% a year
| Term | Monthly EMI | Total interest | Total you pay |
|---|---|---|---|
| 5 years | ₹20,517 | ₹2,30,992 | ₹12,30,992 |
| 10 years | ₹12,399 | ₹4,87,828 | ₹14,87,828 |
| 15 years | ₹9,847 | ₹7,72,531 | ₹17,72,531 |
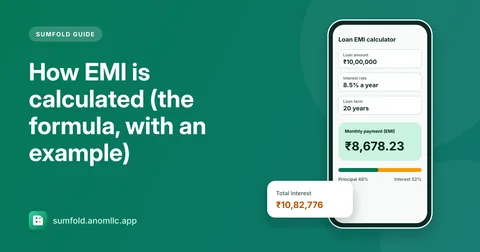
| 20 years | ₹8,678 | ₹10,82,776 | ₹20,82,776 |
| 25 years | ₹8,052 | ₹14,15,681 | ₹24,15,681 |
| 30 years | ₹7,689 | ₹17,68,089 | ₹27,68,089 |
Going from 20 to 30 years lowers the EMI by under ₹1,000 a month but adds about ₹6.85 lakh of interest. The EMI falls more and more slowly as the term grows, while the interest keeps climbing.
Why longer loans cost so much more
Interest is charged every month on what you still owe. With a long loan, the balance stays high for longer, because the early EMIs are mostly interest. The EMI formula guide shows how the first payment of a 20-year loan is about 80% interest.
How to choose a term
- Start from what you can pay every month, with room for emergencies. Many lenders look at whether all your EMIs together stay under roughly half of your take-home pay; a lower share is safer.
- Pick the shortest term with an EMI in that range. In Sumfold's Loan EMI tab, try a few terms and watch the total interest.
- Keep the option to prepay. If you choose a longer term for safety, paying extra when you can (a bonus, a raise) brings much of the saving back. Check your loan's prepayment charges first.
Shorter term or prepayments?
A shorter term forces the saving; prepayments keep it flexible. If your income varies, a slightly longer term with regular prepayments can be the calmer choice. If you know you'll pay, a shorter term usually costs less overall, and floating-rate home loans in India generally can't charge individuals for prepaying.
Try it with your own numbers
Open Sumfold, choose Loan EMI, enter your amount and rate, and switch the term between years and months. The payment schedule shows how much interest each year costs, which makes the trade-off easy to see.